We’re in the early innings of a gold major acquisition phase.
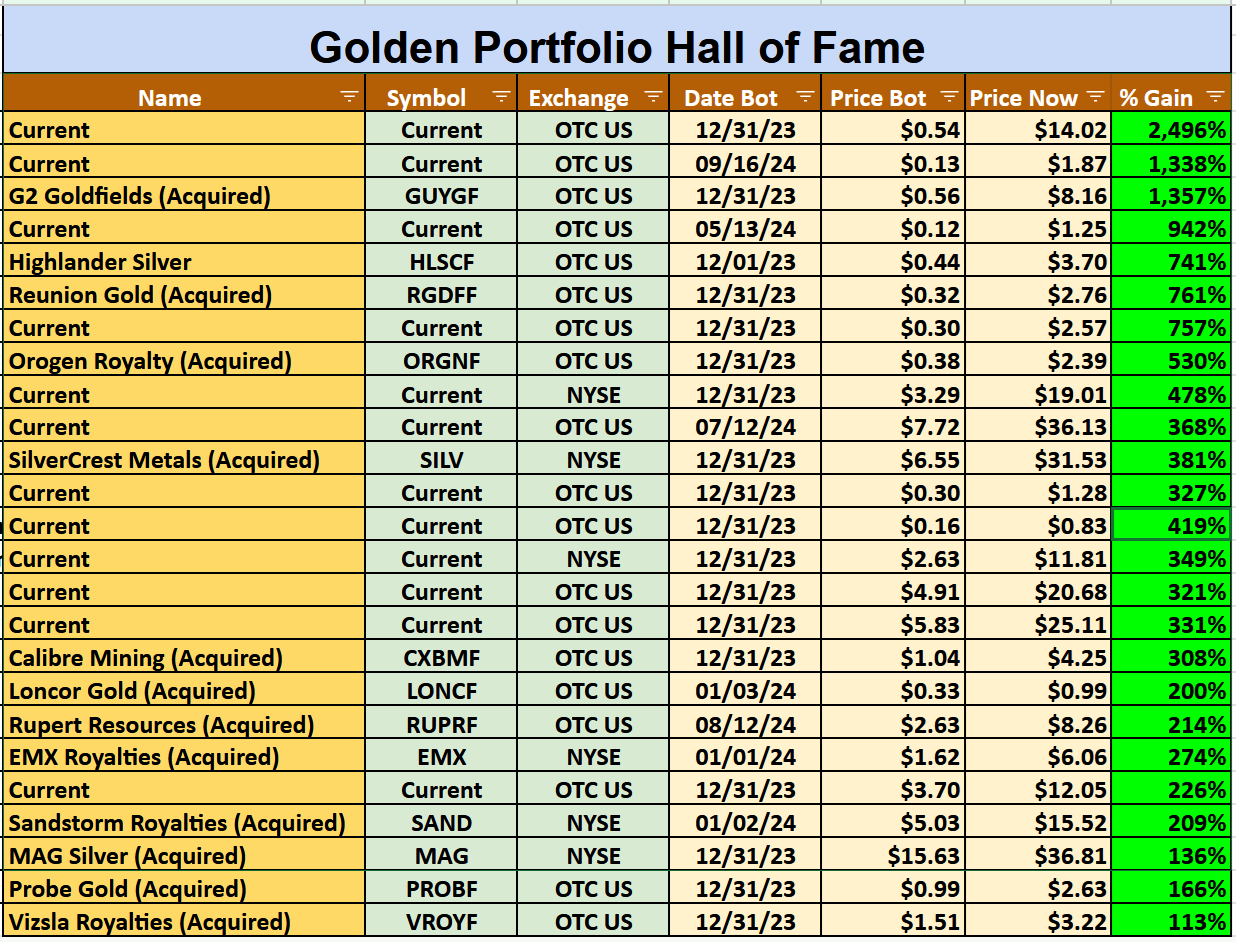
Over the past year, I’ve seen an acceleration of junior explorers/developers and miners acquired from my portfolios. I’ve seen 10 companies taken over in just the past year or so.
Acquisitions are a sign that gold majors’ fears over running out of gold to mine have overtaken their fears of overleveraging themselves to buy new mines.
By the end of this bull market, gold majors will be reckless. They’ll spend far too much on “moose pasture” properties with little gold and less promise to ever get it out of the ground.
In 2012, some of the largest gold majors went way overboard with acquisitions. Barrick Gold nearly went bankrupt, and is still paying for a bad deal it made – 14 years later.
But right now, we’re just starting to see a new acquisition phase take off.
As you know: gold mines are wasting assets. Every ounce of gold that comes out of the mine is one fewer it can mine later. So the only way for gold majors to continually create revenue is to continually fill the hopper by either exploring and developing their own properties, or buying smaller companies that have done the exploration and development work for them.
Those smaller companies are what I spend 90% of my time analyzing, because as an individual analyst, I can create information asymmetry by finding value in small, out of the way opportunities that larger investors don’t have time for.
The problem for us is that when a gold major comes in and acquires a smaller firm we currently own (even at a premium), it means we miss out on the upside potential of seeing a mine through the development stage to completion.
Acquired shares get converted into shares of the larger company, and the returns are watered down by the total return of the rest of the larger company’s assets.
The ideal takeover scenario is that a company keeps its cards close to its vest. It slow-rolls resource estimates. It delays economic assessments.
It does the work to prove its resource, economics and feasibility, quietly.
Internally, the company fires on all cylinders. Leadership is focused on building value, not hype.
Hype means attention from majors – and it can mean an early takeover of a project that we, as current shareholders, would prefer to see run for a bit longer.
Normally, these junior outfits are so excited by their own prospects that they scream their findings from the rooftops… and get bought out shortly thereafter. An early exit means a lot more potential value left on the table – or more accurately: swept off the table into the gold major’s pockets.
And I should back up – and clarify: I’m not complaining about our companies that have been acquired. Sometimes these acquisitions are right on time and we’ve done very well, like when G2 Goldfields was taken over by GMining for a 1,092% gain earlier this year…
That’s exactly what we want. Could G2 have run a bit further? Maybe…
There’s no way to know.
What I do know: I’m about to add a new company to my Golden Portfolio IV service that’s another “sleeper” takeover candidate.
It’s still a small company, and it’s doing the resource and economic work right now, but keeping it quiet.
I will be adding this company to GPIV on October 1st – but you can get access to my research on it, today.
I’ve just put together an investment brief I think you’ll want to see.
Click here to read my investment brief on this “sleeper” acquisition target.
Best,
Garrett Goggin, CFA, CMT
Lead Analyst and Founder, Golden Portfolio