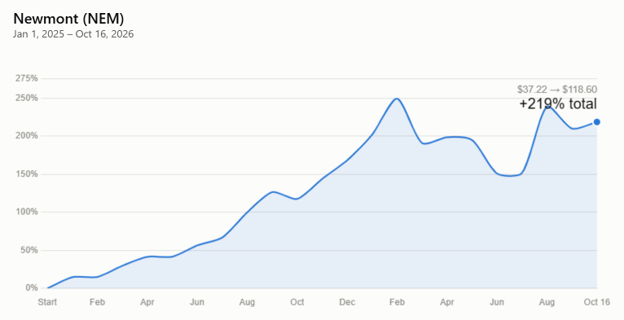
Early in 2025, I pointed out that gold miners like Newmont were undervalued.
Newmont has since soared more than 200%.
Today, the value proposition is not with miners. It’s with other types of gold stocks – and that’s good news for readers like you.
First off, I want to be very specific about terminology here, because it’s important to get these things straight.
In the gold stock sector, you have very different types of companies all operating under the banner of “gold” and it’s easy for investors to blur the lines so as to make these different companies all merge together.
Not all gold stocks are the same. You can’t treat them as a monolith.
Miners are typically the larger and more developed gold firms that are relatively easy to evaluate because they’re in active production, they have earnings/revenues and you can build a very simple model to determine if they’re expensive or cheap.
Even now, people will look at Newmont’s cost per ounce to mine (which is around $1,700/oz as of Q2 financials) and conclude that with gold over $4,100/oz, the company must be a great bargain.
But that’s not how valuations work. It’s not enough to find a profitable company – you must also buy it at an appropriate price. Right now, the value just isn’t there.
For one, the company’s costs to mine gold rose more than 50% between Q1 and Q2. We don’t have Q3 numbers yet (they come out later this week), but it’s likely we’ll see another bump thanks to diesel prices/general inflation rising.
At the same time, the price of gold fell 10% since the end of Q1.
To re-cap: Newmont now sells for more than it did at the end of Q1, even though gold’s price is down 10%+ and costs soared more than 50%.
The value I pointed out in early 2025 is no longer there. You don’t have to be a CFA to see the disconnect.
And look, I’m not picking on Newmont.
Big companies like Newmont have dozens of Wall Street analysts providing coverage. There’s no secret or information edge to be had by looking at Newmont’s cash flows and projected earnings.
That’s why the bulk of the companies I cover in my paid services are not gold miners.
Why? Because the value proposition in these gold miners (which again, are usually well covered/understood by Wall Street) is simply not very attractive.
I mostly cover smaller companies that are not yet producing or mining gold.
Before mining, you have to develop a mine. Before developing a mine, you have to find it.
So, I cover companies that are in different stages of exploration and development. Sometimes these companies are also in early stages of mining, but are not yet hitting their stride, or are mining on a small scale as a way to provide cash flow for a much larger mine’s development.
All of these companies are mostly or completely out of the scope of coverage by Wall Street investment banks or hedge fund analysts.
There’s a massive value to finding these kinds of companies BEFORE they go into active commercial production. The market does not understand how to value these companies. They have very little, if any, analyst coverage.
I’m one of a handful of analysts in the whole world doing this kind of high-level analysis into these firms. In other words, I have a real information edge.
And right now, the value is in the developers and explorers – not the gold miners. I should also mention, there’s a ton of value in gold royalty firms – another category worth your time.
Again, I want to be clear: if you want to succeed as a gold stock investor, you have to know where to find value at any given time. It’s likely that we’ll see value in gold miners in the coming years – but for now, it’s just not there.
I hate to say I told you so about Newmont because you can’t go back to early 2025 and buy shares – but right now, I’m telling you so about these other gold stocks.
Best,
Garrett Goggin, CFA, CMT
Lead Analyst and Founder, Golden Portfolio