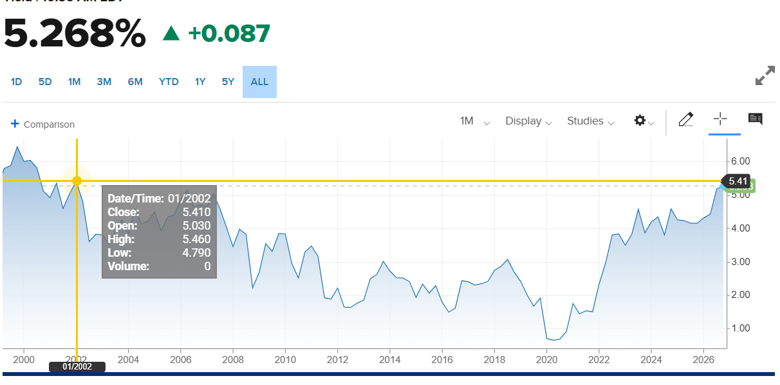
Yields are surging, with the 10 year US Treasury bond now yielding more than 5.2% – a 26 year high.
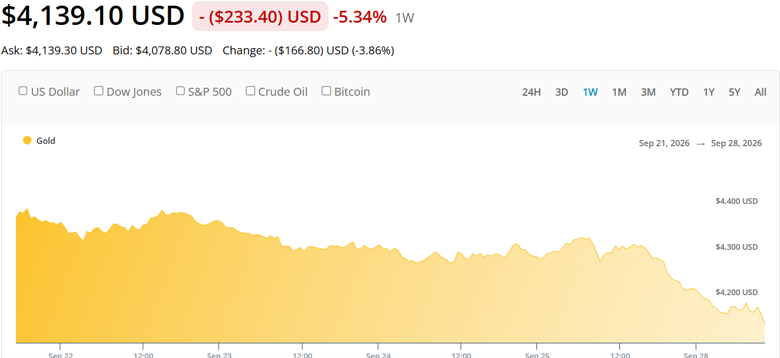
Gold is now falling in price, which is understandable as a short term reaction to higher Treasury yields. Gold prices are dependent on how gold compares to other monetary assets.
When yields rise, it makes US Treasury assets more appealing for some investors. At the margins, it means some people are ditching gold in favor of bonds.
At the same time, we’re seeing a bit of a disconnect of the valuations of gold majors. For years, valuations of major gold miners lagged well behind moves in the price of gold.
But lately, we’ve seen gold major valuations creep up, even as the price of gold went down $1k since Q1.
It’s true that many large cap miners are gushing cash even at $4100/oz – but it’s not enough to simply look at profits. Even the world’s best company with sky high profits has a price that’s too high to pay.
Right now, gold majors are looking a bit stretched:
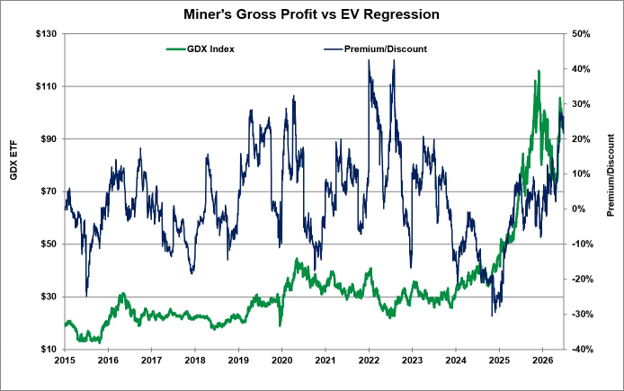
Between 2023 and 2025, gold majors were selling at discount to their cash flows. And we’re in kind of a limbo right now before Q3 earnings – which will reflect the much higher diesel prices we’ve been seeing for the past month or so.
Every open pit mine (the largest and most common mines run by the gold majors) has diesel price sensitivity, because diesel amounts to about 25% of the cost input for these types of mines.
For years, I told people to buy shares of Newmont – because it was selling for a massive discount:
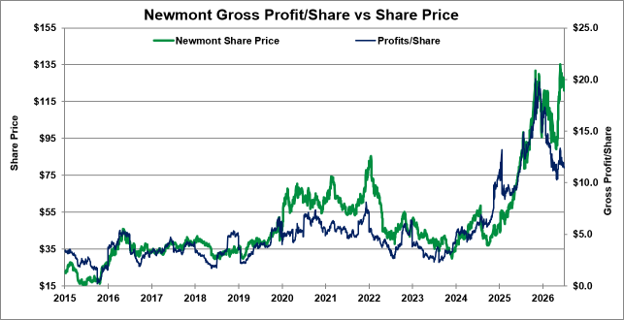
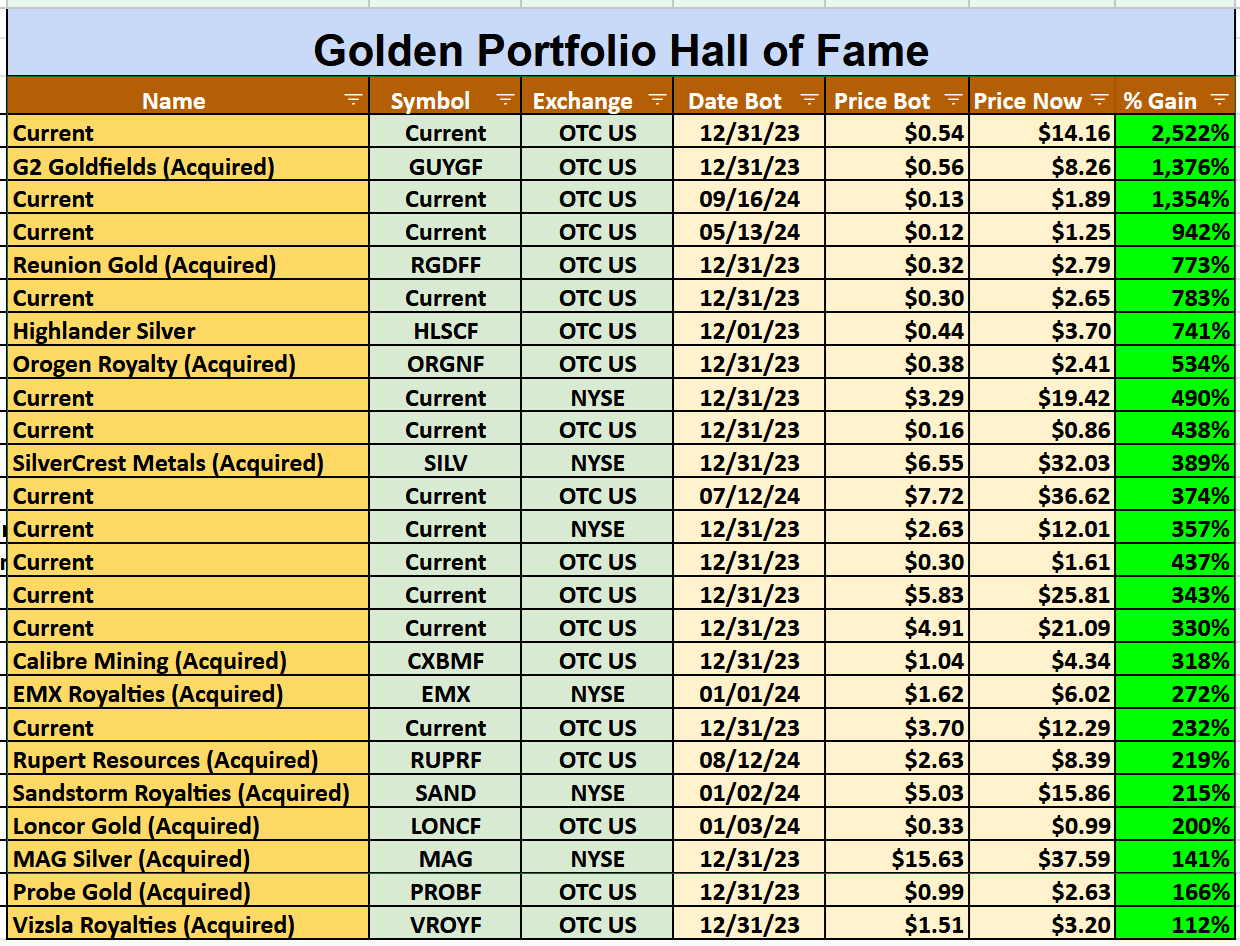
If you bought back in 2024-2025 when I was banging the table, you are up ~300%.
But today, it’s a different story. Newmont is still gushing cash, yes – but the price you pay for that cash has risen considerably.
If you’re a long term gold bull, then maybe this kind of focus on valuation seems pointless. But look: you and I are not in control of the price of gold, or Newmont’s future cash flows or the price of diesel or the 10 year US Treasury Yield.
The factors in our control are very limited. The biggest one is: the price we pay for the value we get. Since it’s one of the few levers we have control over, we must use it to our greatest possible advantage.
That means, for better or worse, we have to look at valuation, even if we’re gold permabulls – because the alternative is to deploy capital based on factors outside of our control.
Throwing money around like that is not investing. It’s speculation.
The good news is you don’t have to guess – because there are still a wide swath of gold stocks that have an excellent value proposition.
One of the more obvious areas to focus on is the gold royalty sector. These companies lock in long term deals to get gold streams and royalties at fixed costs. They don’t care about diesel prices.
Another obvious place to look is at gold juniors that are likely takeover candidates.
On that front, I’m adding a brand new takeover candidate to my Golden Portfolio IV service this week on October 1st.
You can click here to get access to my research into this company now.
Best,
Garrett Goggin, CFA, CMT
Lead Analyst and Founder, Golden Portfolio